


The Interest Inflection: Global Economic Outlook 2026 and Your Savings
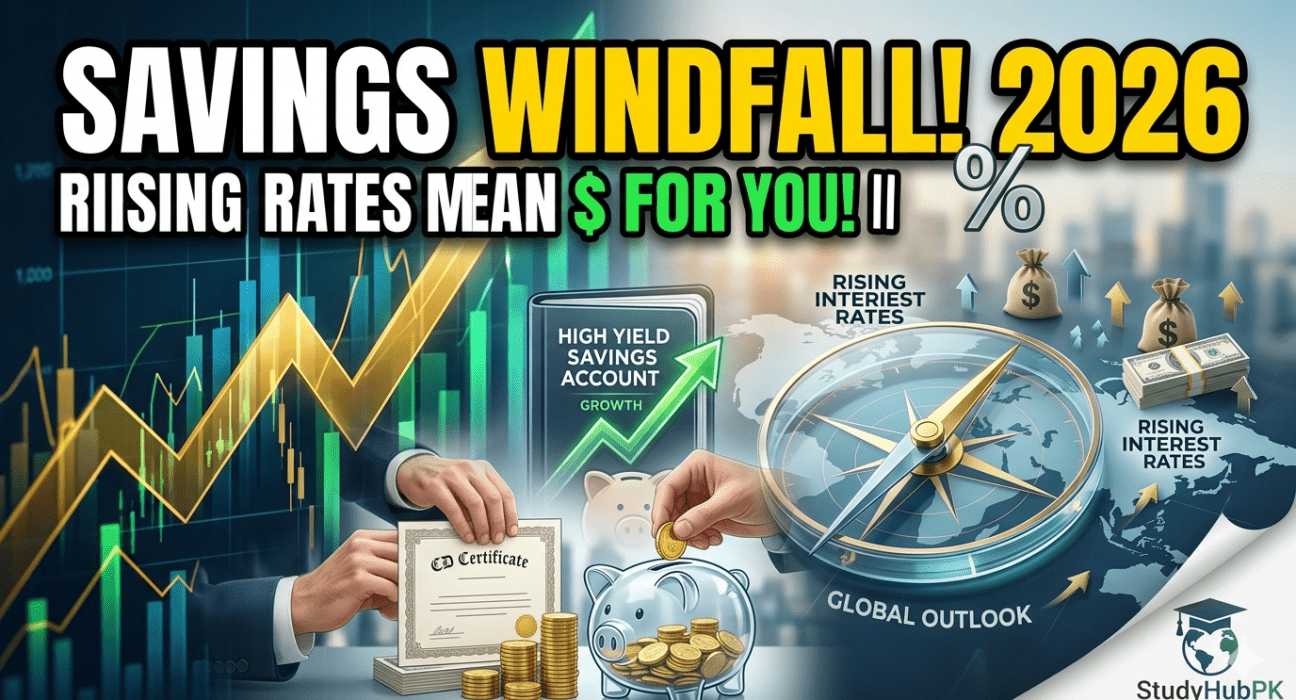
As we move through 2026, the global economic landscape is being reshaped by a sustained period of elevated interest rates. Central banks across major economies have maintained a hawkish stance to anchor inflation, fundamentally altering the “math” of personal finance. For the average saver, this shift represents the most significant opportunity in over a decade, but it requires a strategic departure from the low-yield habits of the past.
The Mechanics of the 2026 Rate Environment
The 2026 outlook is defined by “higher-for-longer” policies. While inflation has stabilized in many regions, the cost of borrowing remains high to prevent secondary price surges. This environment creates a direct windfall for liquid assets:
- High-Yield Savings Accounts (HYSA): With benchmark rates sitting at multi-year highs, HYSAs have become a primary vehicle for wealth preservation, offering returns that finally outpace the cost of living.
- The Return of the CD Ladder: Certificates of Deposit (CDs) have regained their status as essential tools. Investors are increasingly using “luring” strategies—staggering maturity dates to capture peak rates while maintaining periodic access to cash.
- Fixed-Income Resurgence: Government bonds and high-quality corporate debt are providing yields not seen since the pre-2008 era, allowing retirees and conservative investors to generate meaningful income without venturing into high-risk equity markets.
Strategic Adjustments for Savers
In this climate, “lazy money”—cash sitting in traditional checking accounts earning near-zero interest—is effectively losing value. The 2026 strategy focuses on velocity and placement. Moving emergency funds to sweep accounts or money market funds can result in a 4-5% difference in annual yield. Furthermore, the rising rate environment typically precedes a cooling of the housing market, making this a critical period for those saving for a down payment to maximize their “interest-on-interest” gains.


